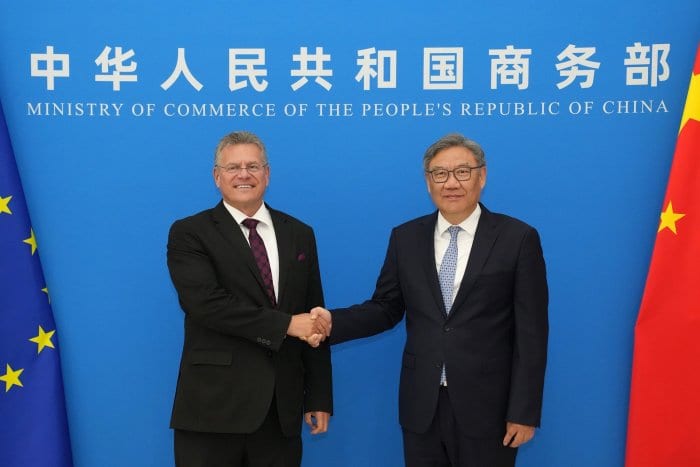

Goldman Sachs upgraded Nio to ‘Buy’ from ‘Neutral’ with a 12-month price target of $7 on Friday, according to StreetInsider, adding to a rally in US-listed Chinese carmakers after the European Union and China reached an understanding on hybrid exports.
Nio makes only fully electric vehicles and exports no hybrids to Europe, so the hybrid understanding does not cover its cars, which still pay the EU’s countervailing duty on China-built EVs.
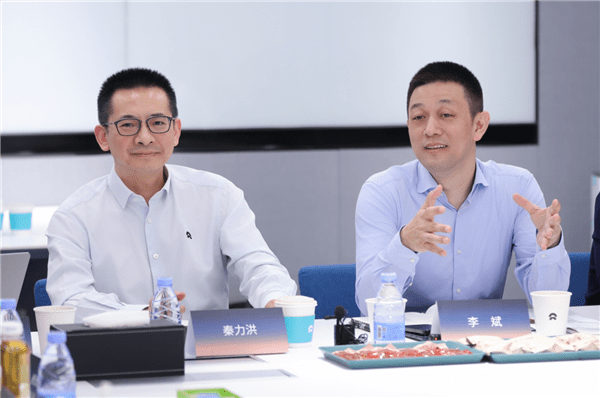
Founder and Chief Executive Officer William Li has repeatedly said Nio will make only battery-electric vehicles.
“I estimate that globally, only two companies focus exclusively on pure electric vehicles, and Nio is one of them,” Li said in December 2025.
After launching Onvo’s L60 in September 2024, he said Nio would “only discuss extended-range vehicles when Tesla adopts that approach.”
Goldman analyst Tina Hou had already rated Nio ‘Buy’ since July 13, however, and StreetInsider‘s own rating history still listed her September 4 target of $6.10 as Goldman’s latest action, so it is unclear whether Friday’s report reflects a new note.
The report cited Hou as saying Nio was positioned to deliver one of the fastest volume growth rates in Goldman’s coverage, with a premium margin profile and a strong profit and free cash flow turnaround through the rest of 2026.
It pointed to Nio’s third-quarter deliveries of 109,178 vehicles, up 25.4% from a year earlier, and September deliveries of 37,408.
Nio’s shares rose as much as 6.5% to $3.63 a day after hitting a 52-week low, and traded at $3.60 at 12:37 p.m. in New York, up 5.6%.
Li Auto was up 6.7% and XPeng 3.8% at the same time, after gaining 7.7% and 5.8%, respectively, in early trading following the EU-China announcement.
Hou has rated Nio ‘Neutral’, ‘Sell’, ‘Neutral’ again and ‘Buy’ since taking over the bank’s coverage in January 2024, but the stock has fallen about 25% since her upgrade in July.
Her Hong Kong target stood at HK$48 ($6.12) after the September cut.
Hou also covers Li Auto and XPeng for Goldman, according to notes archived by the CARBA-owned Price Target, an archive of Wall Street analyst research that reproduces notes on AI, semiconductor and automotive stocks.
Hou is a Vice President and Head of China Autos Equity Research at Goldman Sachs, based in Shanghai, according to her LinkedIn profile.
The analyst has been at Goldman since March 2010, after two years of multi-industry research at McKinsey & Company, her profile says.
Goldman Sachs was among the joint underwriters of Nio’s initial public offering in New York in September 2018, which was priced at $6.26 per share.
Hou’s January 2024 note was described as an initiation, which indicates Goldman’s coverage had lapsed after 2021.
How the Stock Has Traded
Nio’s ADRs fell to $3.36 on Thursday, their lowest intraday level since June 2025, and closed at $3.41. On October 2, the shares closed at $3.37, their lowest close since April 2025.
Nio’s highest close of 2025 came on October 2, at $7.89, after an intraday high of $8.02.
This year, the shares peaked at a close of $6.87 on April 16 and touched $7.00 the next day, and Thursday’s close was about 50% below that level.
Nio has lost about 29% so far in 2026, from $5.10 at the end of 2025.
The shares fell 32% in the third quarter, including 19% in September alone.
Nio’s lowest point in the past two years was $3.02, touched on April 8, 2025, during the market selloff that followed US tariff announcements.
The Current Buy Call
Hou upgraded Nio to ‘Buy’ on July 13 with a $7 target and HK$55 ($7.01) for the Hong Kong shares, up from $6.60, according to Der Aktionär and other outlets.
“We upgrade Nio to Buy with 12-month DCF-based target prices of US$7.0/HK$55,” Hou wrote in the note.
She said the new ES8 and ES9 SUVs had strengthened Nio’s premium position and created “a higher competitive moat,” and she expected a similar strategy to revive the 5 and 6 series from 2027.
Hou forecast 2026 volume growth of 43%, revenue growth of 60% and a non-GAAP net profit of 1.6 billion yuan ($238 million), against a loss of 12.4 billion yuan ($1.85 billion) in 2025.
She also expected free cash flow to swing to 12.1 billion yuan ($1.8 billion) from an outflow of 3.1 billion yuan ($462 million).
The shares closed at $4.78 the trading day before the upgrade.
Seven weeks later, Hou cut her target to $6.10 and kept the Buy rating, after Nio’s third-quarter guidance fell short.
Nio’s volume guidance was about 11% to 12% below consensus and its revenue guidance about 7% to 8% below at the midpoint, Hou said in the September note, citing weak domestic demand and low recognition of the Onvo brand.
She lowered her 2026 to 2028 non-GAAP net profit forecasts to between 0.6 billion yuan ($89 million) and 3.6 billion yuan ($536 million), from between 1.6 billion yuan and 5.3 billion yuan.
Hou still expected a 2026 gross margin of 18.6%, up from 13.6% in 2025, and free cash flow of 7.1 billion yuan ($1.06 billion).
Her $6.10 target sits in line with the Street, where the average target over the past 12 months was $6.11, according to StreetInsider, which counts 18 ‘Buy’, seven ‘Neutral’ and two ‘Sell’ ratings on the stock.
JPMorgan cut Nio to ‘Neutral’ from ‘Overweight’ on September 1, while Barclays rates it ‘Underweight’ with a $4 target.
Hou’s Record on Nio
Hou initiated coverage in January 2024 with a $8.40 target, citing a “relatively light new model pipeline” and Nio’s falling share of China’s premium market. The shares traded at about $8.05 at the time.
In October 2024, she raised her Hong Kong target to HK$38 ($4.84) from HK$34 ($4.33) while keeping a Neutral rating.
By November 2024, she had cut the stock to ‘Sell‘ with a $3.90 target, citing a limited new model pipeline and a slow production ramp-up at Onvo, its first sub-brand.
Rising sales, marketing and research spending would hinder profitability over the following three years, Goldman said at the time, according to Investing.com.
The shares closed at $4.84 before that downgrade.
Hou cut the target to $3.50 in January 2025, raised it to $3.90 in February and kept the Sell rating.
She moved back to ‘Neutral‘ on June 17, 2025, with a $3.80 target, after the stock had fallen to $3.52, a 27% drop from the price before her ‘Sell’ call.
Hou said then that “management’s cost reduction efforts would help improve the company’s profit levels over the next three years.”
She later raised the target to $4.30 and, on October 30, 2025, to $7, as the L90 and ES8 lifted sales.
“We maintain Neutral rating with limited upside,” Hou wrote in that note, which implied a 2% downside for the US shares.
She brought forward her forecast for full-year non-GAAP operating break-even to 2028 from 2029.
The stock had more than doubled between her June 2025 Neutral call and that note, a rally her rating did not capture.
Her target was later trimmed to $6.60 before the July 2026 upgrade.
The Fei Fang Years
Goldman’s earlier analyst on Nio, Fei Fang, moved the stock through all three ratings in 2020.
Fang upgraded Nio to ‘Buy‘ on June 2, 2020, with a $6.40 target, saying liquidity risks had eased. Three weeks later, after the shares had risen more than 50%, he cut it to ‘Neutral‘ and raised the target to $7.
Fang then downgraded Nio to ‘Sell’ on July 17, 2020, saying “the current share price reflects over-optimism,” according to a Yahoo Finance report.
His $7 target implied a 46% drop from the previous close, but the shares kept rising through the rest of the year.
On December 1, 2020, Fang upgraded Nio to ‘Neutral‘ and raised the target to $59 from $7.70, saying he had “underestimated” the benefits of battery breakthroughs and Nio’s battery-as-a-service model.
Goldman upgraded Nio to Buy again on October 7, 2021, with a $56 target, about 66% above the previous close, citing the ET7 sedan’s potential in the premium segment, according to The Motley Fool.
The shares now trade about 94% below that target.