
Goldman Sachs lowered its third-quarter delivery estimate for Tesla by 11%, citing weaker-than-expected sales data across the automaker’s three largest markets.
Analyst Mark Delaney cut his Q3 forecast to 435,000 vehicles from 490,000 while reiterating a Neutral rating and a $360 price target.
“We believe that Tesla’s 3Q26 vehicle deliveries are tracking below consensus (at 456K per Visible Alpha) and our prior view, and we lower our forecast to 435K from 490K,” Delaney wrote.
Consensus for the quarter stands at 456,000 deliveries, according to Visible Alpha, placing Goldman’s revised estimate about 4.6% below the Street.
Goldman also trimmed its fourth-quarter forecast to 475,000 from 515,000. That figure sits 2.8% above the 462,000 consensus, leaving Delaney below the Street on the quarter he is cutting and above it on the quarter he is not.
Both forecasts imply a sharp decline from the 497,099 vehicles delivered between June and September 2025 — a record quarter for the company, when consumers rushed to purchase ahead of the $7,500 EV tax credit deadline in the US.
At 435,000, the third-quarter estimate is 12.5% below that figure and 9.4% below the 480,126 vehicles delivered in the second quarter.
According to the analyst, “this is based on monthly and/or weekly sales datapoints for key regions (e.g. China, the US, and Europe), and we think that all three regions are tracking slower than we had previously expected.”
Regional Demand Picture
Sales momentum differs sharply by geography, and Goldman’s note reflects a broad-based miss rather than weakness concentrated in a single market.
In the United States, demand has remained flat since the $7,500 federal EV tax credit expired on September 30, 2025.
Tesla sold an estimated 40,816 vehicles domestically in August, a 26% year-over-year decline according to Motor Intelligence data.
Monthly volumes in 2026 have settled into a narrow band between about 37,550 and 42,435 units, well below the 47,000-unit average the company carried through the first half of 2025.
Delaney’s June note had already flagged the domestic trend, noting that quarter-to-date deliveries through May were tracking down mid-teens percent year-on-year per Motor Intelligence.
Europe has moved in the opposite direction.
Registrations through May were running 85% to 90% ahead of a year earlier, on the figures Delaney cited in June, and Germany’s reinstated federal EV purchase incentive added further tailwind after applications opened in May.
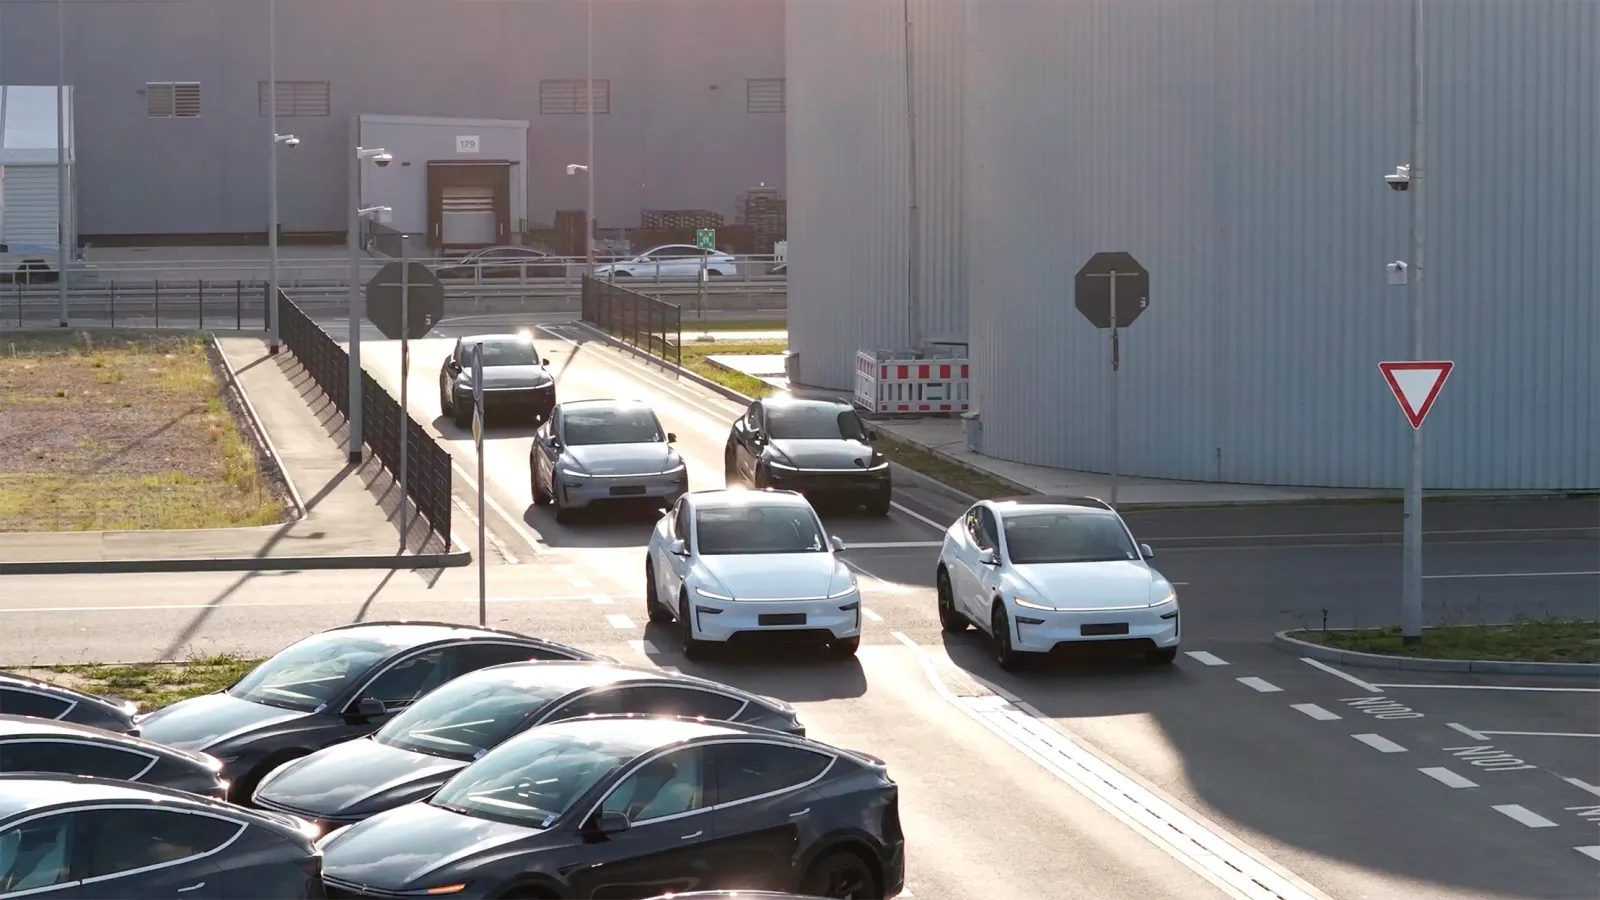
Tesla added special shifts at Giga Berlin in September as the company races to lift weekly output from fewer than 6,500 Model Y units to 7,500 by mid-October, an increase of about 15%.
Still, even a region Goldman had cited as a bright spot in its Q2 preview — where registration data showed year-over-year increases of 85% to 90% through May — appears to have fallen short of the bank’s third-quarter assumptions.
China presents the weakest picture.
Domestic sales fell 12.4% year-on-year in the first eight months of 2026 to 316,251 vehicles, according to CPCA data.
August brought 50,047 deliveries, down from a year earlier and a third consecutive monthly decline.
Tesla launched the Model Y Performance in China on September 5 and began offering direct cash discounts on in-stock vehicles this month — a 10,000-yuan reduction on the Model Y and 5,000 yuan on the Model 3 — moves that signal pressure on domestic volumes.
Delaney acknowledged that some markets supplied via exports from Shanghai are performing better.
“Some regions filled via exports from China (e.g. SE Asia, South America, Australia) are showing strength on yoy basis, which we think will partly mitigate the weakness,” he wrote.
Q4 Outlook
Delaney’s fourth-quarter number requires a 40,000-vehicle step up from the third, or 9.2% quarter on quarter. He pointed to seasonal patterns and the Model Y L ramp as potential tailwinds.
“Typical seasonality in 4Q, plus the Model Y L ramp in the US and Europe, has the potential to help 4Q26 to improve qoq,” he wrote. “We also think that FSD can be a driver of demand.”
Tesla began assigning delivery windows for the six-seat Model Y L in August, with deliveries beginning in September from Gigafactory Texas.
CEO Elon Musk framed Full Self-Driving as a demand driver on the company’s second-quarter earnings call on July 22, telling investors that US buyers were coming into stores wanting FSD.
Q2 Contrast
Goldman’s tone has shifted markedly from three months ago.
In a June 16 note ahead of second-quarter results, Delaney raised his Q2 delivery estimate to 420,000 from 405,000, writing that deliveries were tracking ahead of the 400,000 consensus. Delaney held a $375 price target in that note.
Tesla went on to deliver 480,126 vehicles in the quarter, 60,126 above Goldman’s raised estimate and a beat of 14.3%.
Goldman’s full-year position has moved just as far. Tesla delivered 358,023 vehicles in the first quarter and 480,126 in the second. Adding Delaney’s two revised estimates implies about 1,748,000 for 2026, roughly 117,000 below the 1,865,000 he modelled for the year in September 2025.
Stock Performance
At Tuesday’s closing price of $356.58, the new target implies upside of less than 1%.
Shares have swung widely over the past three months.
From a May peak near $446, the stock sold off sharply through late July to a 52-week low, its lowest level since August 2025
A partial recovery brought shares back above $360 by mid-August before a 6% drop on September 4 following a Cybercab launch event that analysts said underwhelmed expectations.
Goldman’s price target has traced a downward path over the past year. Delaney raised it to $395 in September 2025 and to $425 in October, cut it to $400 later that month, moved to $405 in January 2026, cut to $375 in April, and has been at $360 since around second-quarter earnings.
At $360, Goldman’s target sits just $3.42 above the current share price, implying that the bank sees limited room for the stock to move in either direction at present valuations.