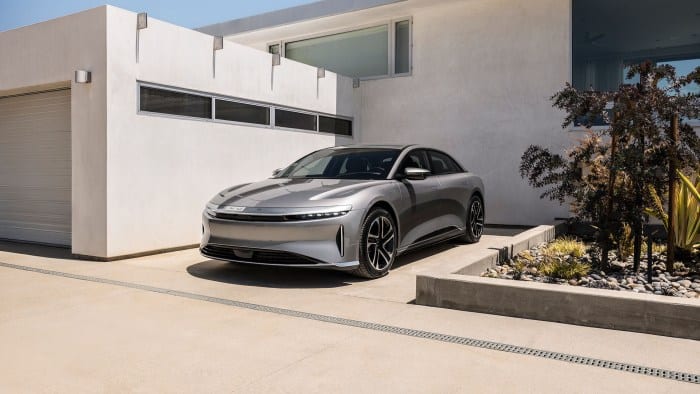

Morgan Stanley cut its price target on Lucid to $3 from $5 on Thursday and kept its ‘Underweight’ rating, extending five years of mostly bearish coverage of the EV manufacturer.
The new target from analyst Andrew Percoco, which was first reported by StreetInsider, is about 9% below the Wednesday’s closing price of $3.29.
Morgan Stanley’s cut is the firm’s third since December, when it downgraded the stock and lowered the target to $10 from $30.
The cut comes ten days after Lucid reported third-quarter deliveries of 3,806 vehicles, down 6.7% from a year earlier, and less than a week after the company disclosed a further $400 million draw on its credit line from Saudi Arabia’s Public Investment Fund (PIF).
Earlier this week, RBC Capital Markets cut its target to $4.
Lucid is due to report third-quarter results on November 9.
Morgan Stanley has rated Lucid ‘Underweight’ for all but about nine months since it began covering the company in September 2021, and its analysts have never recommended buying the shares.
Over five years, the bank’s view has moved from an outright bearish start through a brief neutral period in 2025, when Adam Jonas, then the bank’s Lucid analyst, argued Lucid could become a “socket” for AI, and back to ‘Underweight’ on concerns about losses and dilution.
An Underweight Start
Jonas initiated coverage on September 14, 2021, with an ‘Underweight’ rating and a $12 target, about 40% below the previous day’s close of $20.06.
“Lucid is a highly vertically integrated BEV company that addresses the premium market at Tesla and above,” he wrote.
“However, we find ourselves asking how big is the market for this level of premium EVs and what are reasonable levels of risks that investors should shoulder in order to take what may eventually be only a modest slice of a crowded premium BEV market.”
“At a $31bn valuation, the stock market appears to be ascribing an unusually high probability of scenarios where LCID achieves very high market share, margins or both,” he wrote.
“We think LCID can occupy a sustainable niche place in a difficult market,” he added, while saying the road ahead would likely bring “many obstacles.”
He raised the target to $16 on November 17, 2021, after Lucid’s third-quarter results, while keeping the ‘Underweight’ rating.
On March 3, 2022, he cut the target back to $12 after Lucid lowered its 2022 production outlook to 12,000 to 14,000 vehicles from 20,000.
After the first-quarter results in May 2022, Jonas wrote, “We forecast 9.9k deliveries for FY22 which we believe may be on the aggressive side.”
He described Lucid as “not fully funded” in the same note.
In October 2022, he wrote that “the relationship between the Kingdom of Saudi Arabia (KSA) and Lucid could extend beyond a controlling shareholder status.”
‘Really Nice Car’
In January 2023, after Tesla cut prices by up to 20% in the US and Europe, Jonas halved his target to $5 from $10, calling the cuts “just the latest sign the EV market may be entering the ‘shake-out’ phase.”
He wrote that Lucid “builds cars for more than they sell them for.”
“As other EV manufacturers grind car prices lower, we think Lucid would need to react by lowering ATPs alongside them (making their loss-making vehicles even more loss-making), and/or brace for lower unit sale volumes,” he wrote, referring to average transaction prices.
On January 31, 2023, he summed up his view as “Really nice car, large cap valuation, niche market, continued cash needs.”
“In the wake of Tesla’s price cuts, we would be prepared for potentially further declines in reservations, assuming they are still reported,” he wrote.
“Taken together with SBC impact, we have forecasted a further 25% increase in LCID diluted shares outstanding through FY26,” he added, referring to stock-based compensation.
He also wrote that “forthcoming manufacturing innovation at rival Tesla could drive a step-change in EV deflation.”
After the fourth-quarter results in February 2023, he said, “We remain fans of LCID’s innovative technologies and talented management team.”
“Unlike many other startups, the company has shown an ability to deliver a compelling product to the end customer,” he said, while warning that “the high price point of most of the Lucid Air vehicle line is proving to attract a more limited addressable audience.”
He reiterated the ‘Underweight’ rating and $5 target in July 2023.
The target stood at $4 in February 2024, according to TipRanks, and at $3 by late 2024, when Jonas wrote that Lucid’s third-quarter results “did not materially change the narrative or our assessment of risk/reward for LCID shares.”
The ‘Socket’ for the AI ‘Brain’
In March 2025, Jonas upgraded Lucid to ‘Equal-weight‘, kept the $3 target and set a $10 bull case, and the shares rose more than 14% in early trading on March 18.
“More than an ‘EV 1.0’ automaker?” he wrote.
“Following the announced/ongoing changes in leadership, we believe Lucid has opportunity to execute an AI strategy leveraging strategic/sovereign partnerships within the context of the urgency to develop onshore manufacturing capacity for BEVs as the ‘socket’ for the AI ‘brain’.”
“We believe that at this stage, the risks to upside are more equilibrated with the risks to downside for Lucid shares,” he wrote.
“It’s difficult for us to see how near term quarterly results introduce new negative information that a bearish consensus doesn’t already expect.”
He also wrote that Lucid’s access to capital and strategic relationships could “uniquely position Lucid to straddle geopolitical hurdles in potentially partnering with both China and the West.”
When Lucid announced a robotaxi partnership with Nuro and Uber in July 2025, Jonas reiterated his ‘Equal-weight’ rating and called it a possible first of many strategic deals.
“Electric machines are the corporeal ‘sockets’ for AI brain,” he wrote.
“While $300mn in new equity funding from Uber equates to <1 quarter of cash burn for LCID, the investment may help to better align incentives between the two companies while providing modest financial cushion as Lucid ramps production of Gravity,” he wrote.
The bank moved its target to $30 on September 2, 2025, the day Lucid’s shares began trading after a one-for-10 reverse split, leaving the rating unchanged.
Back to Underweight
By December, coverage had passed to Percoco, who downgraded Lucid back to ‘Underweight’ on December 8, 2025, and cut the target to $10 from $30.
The downgrade came with an outlook in which Morgan Stanley described the US EV as heading into an “EV winter” in 2026, according to Barchart.
“Lucid’s premium positioning and higher ASPs help buffer near-term volatility from the loss of EV tax credits relative to other mass-market EV OEMs,” Percoco wrote.
He said Lucid’s “path to profitability hinges on successfully scaling its more affordable midsize platform,” with production due to start in late 2026 and ramp in 2027.
He wrote that “we do not forecast Lucid to reach gross profitability until 2028,” adding that EBIT losses per vehicle would improve “from $216k/vehicle in 2025 to $126k in 2026” but “persist until 2031.”
“In the interim, we see significant dilution risk for shareholders as we estimate it will need to raise ~$2bn of equity by 2H26 (relative to its $4.6bn market cap),” he wrote.
On May 6, 2026, after Lucid’s first-quarter results, Percoco halved the target to $5 and kept the ‘Underweight’ rating.
On that quarter’s earnings call, he had pressed management on free cash flow and liquidity through at least the second half of 2027.
Then-Chief Financial Officer Taoufiq Boussaid replied, “You need to recall that there is a typical seasonality in the company,” linking the first-quarter cash burn to a stop-sale on the Gravity SUV.
Morgan Stanley kept the ‘Underweight’ rating and $5 target through the summer, including after Lucid’s second-quarter results in August, before Thursday’s cut.
How the Calls Played Out
At $3.29, Lucid’s shares are worth the equivalent of about $0.33 before the reverse split, about 98% below their close the day before Morgan Stanley’s initiation.
They are about 85% below their level before the March 2025 upgrade, based on the 39% upside that Jonas’s $3 target implied at the time.
The shares have fallen 68.7% year to date based on the $3.32 price the stock was trading at as of publication time.